Tag: Finance

Passion Investments & NFTs

By Anya Cooklin-Lofting

For many, investments of passion are a welcome balm to the complexities and intangibilities of more traditional investment categories like stocks and bonds. At their most basic, passion investments involve the purchase of items you love that tend to be defined by their rarity, quality, cultural or aesthetic value and of course, their demand. It is all about investing in alternative kinds of assets that bring you more than just a return on your investment should you choose to sell. In other words, such investments offer investors the chance to enjoy the items under their care. 
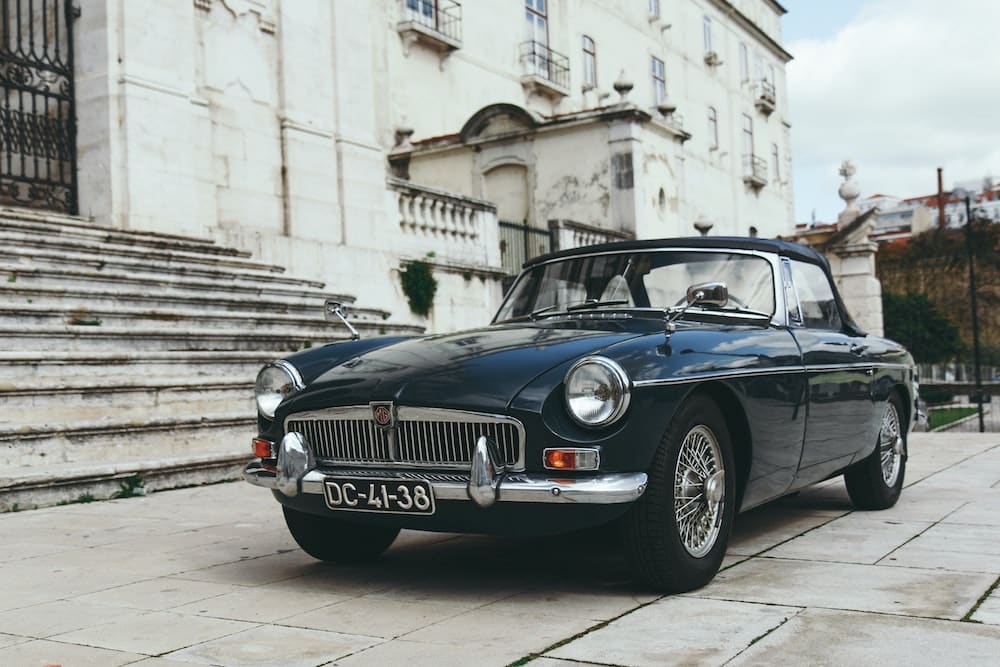
Typical passion investments include art and furniture, jewellery, coins and cars, which generally demonstrate an increase in value over time, or at least tend to hold their value. Because passion investors aren’t guaranteed a return, it’s important to look at how different passion investment categories have performed over the last couple of decades to help inform their purchases. However, investments of passion do tend to perform well during periods of economic uncertainty because the value of passion asset classes doesn’t undulate with the rise and fall of potentially unfavourable stock markets. In this way, passion investing proves to be a sensible, enjoyable and rewarding way to diversify your investment portfolio. 

The best part about investing, and investing in passion asset classes more specifically, is that you don’t have to be an ultra-high net worth individual to get involved. While there are some categories that demand a certain amount of wealth due to the nature of the assets (such as classic cars), the majority offer entry-level investment opportunities for every budget.
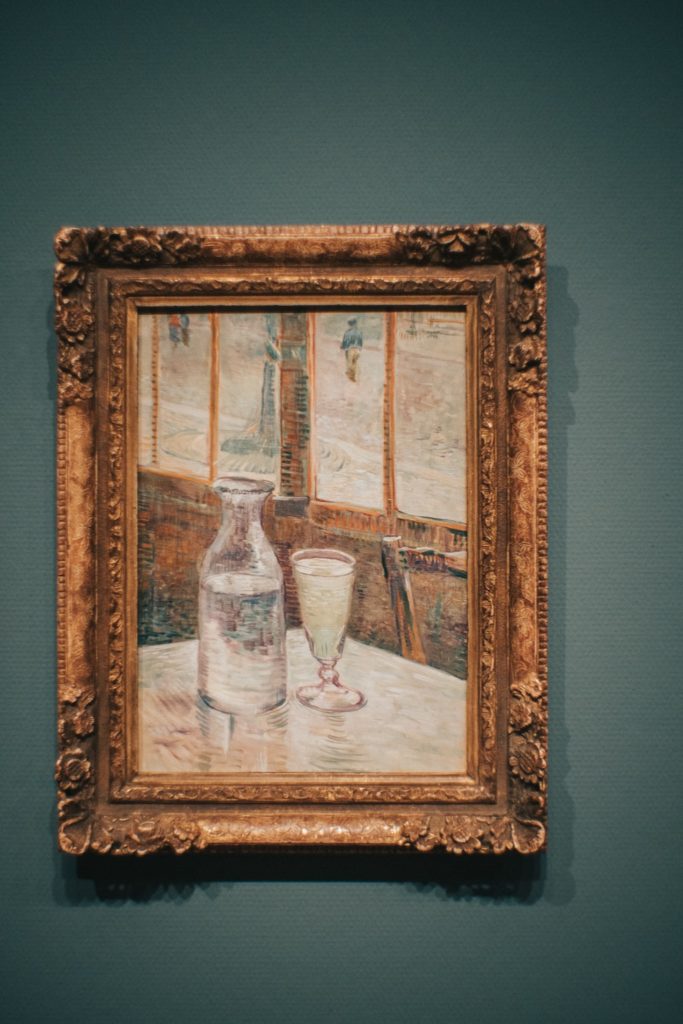
Fine art is the best example of a passion investment that feels at once democratic and exclusive depending on the financial commitment you’re happy to make. Although there is no guarantee that your investment will pay off, you’ll be able to enjoy the art while you own it and bide your time while tastes and demands fluctuate. 
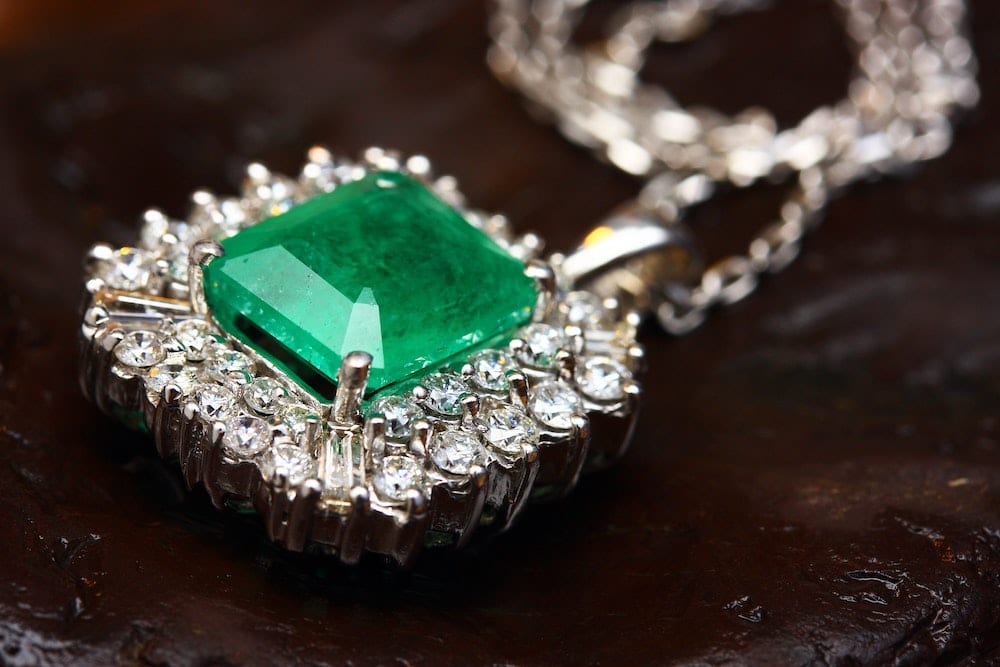
The same principles can be applied to antique and designer furniture or jewellery. Our collective, quickly changing tastes and preferences adversely affect the valuation of these kinds of assets. The best thing to do over and above enjoying your purchases is to keep them safe, clean and out of direct sunlight.

The more progressive, experimental set of passion investors, however, are turning to other asset classes. Designer trainers, for example, have come into their own as an investment category, hence the £22,783 price tag attached to the Kanye West X Louis Vuitton collection. But one of the most headline-grabbing passion investment options is in Non-Fungible Tokens or NFTs, which allow passion investors to own digital assets. 

In the midst of the pandemic in March 2021, market tracking revealed a collective spend of US$200 million on NFTs including artworks, memes and gifs. Fundamentally, an NFT is a non-interchangeable, non-replicable asset, making it more similar to a piece of art in the physical world than the cryptocurrency one would use to buy it. 
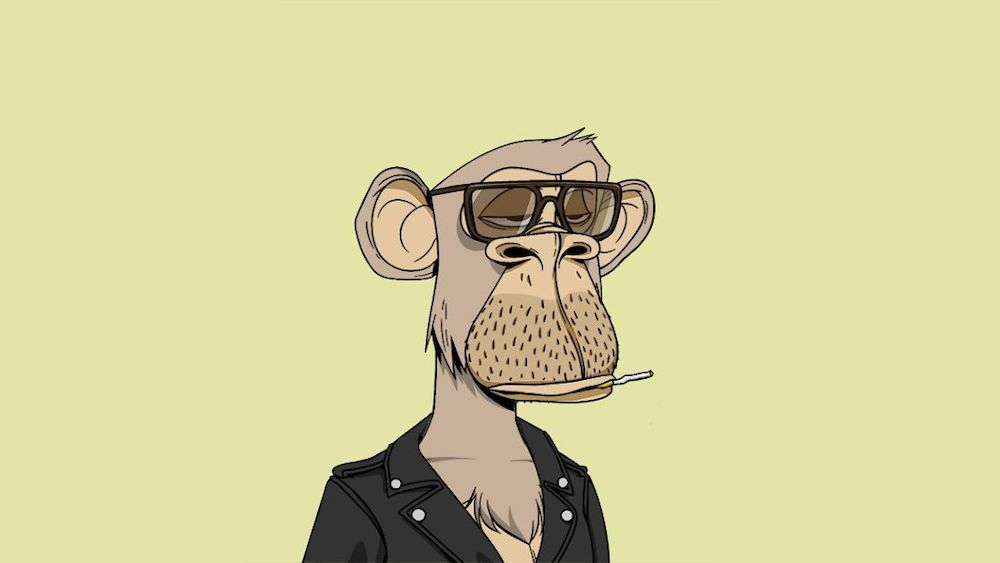
This is well summarised the popularity of ‘Bored Ape’ NFTs, a limited edition of 10,000 artworks with different unique traits and qualities, owned largely by super-rich musicians and sports personalities and created by the application software developer, Yuga Labs. The very human act of art-buying is driven by aesthetics; we buy the art that speaks to us, and this is also how passion investors pursue their NFTs, and Bored Apes in particular. But on a wider, slightly more psycho-sociological level, Yuga Labs has created a brand-led community in the same way that other luxury brands have done, giving wealthy participants in the community a sense of belonging and prestige. They have successfully built a digital community that uses a heady cocktail of ‘hype’ (as celebrities publically invest in their NFTs) and new technology to charm an audience and persuade people into passion investments that serve to express their digital identities. 

In the same way a passion investor in physical fine art might collect works from a narrow artistic movement, era or style to say something about who they are in the world, NFT investors are investing in works that inform their digital presence. All of us with any disposable income have those things in our lives that feel like part of the collage of ‘stuff’ that makes up our curated personalities. NFTs are just an extension of that phenomenon but in the digital world. 

The Benefits of Investing in PR

By Anya Cooklin-Lofting

Ironically, the public perception of public relations is inaccurate. For an industry so concerned with the positive reputation of its clients, its own image in the mainstream has been warped, defined by uproarious recalcitrants like Samantha Jones, Malcolm Tucker and Edina Monsoon. The reality of PR has less to do with shambolic Champagne receptions, ludicrously late nights and even later mornings, and more to do with strategic planning, creative, critical thinking and compelling storytelling. 

At its most basic, PR is the framework for the interaction between companies and their customers via the media. When you instruct a PR agency or a consultant, you are trusting them to tell your brand story to the right journalists at the right time to help position your brand, services and products in the magazines your audiences read. This generates awareness in your key demographics and, eventually, commercial gain. 

PR holds sway. It is an effective way to authentically spotlight your company from the respected position of third-party endorsers – the press. Unlike advertising, the only financial exchanges should be between you and your PR expert, and the journalist and the media house they’re writing for. In other words, your PR coverage is earned based on the integrity and value of the story you are telling; no money is exchanged between you and the journalist. In this way, investing in PR is one of the most genuine approaches to implementing a meaningful media campaign. It is also one of the most economical: your monthly spend with an agency or a consultant will almost certainly be much lower than if you were to consistently buy media space, especially from high-circulation magazines or websites.

However, high circulation coverage won’t always be a marker of success, as the kind of media coverage you are aiming for will differ greatly depending on the audiences you want to engage. There is no one-size-fits-all option and key performance indicators vary greatly between campaigns and from business to business. More often than not, titles that boast high circulation and a global reach might not be right for your business. For example, a huge, glossy, double-page spread in Vogue could be less successful for your company in terms of conversions or website traffic than a great piece in a niche magazine with a readership that’s more responsive to your services or products. 

Despite the distinct qualities and nuances of different campaigns, the uniting ingredient of each is a solid understanding of target audiences. Your PR agency must fully understand the behaviours, passions and pastimes of your existing and prospective customers, such as the magazines or websites they read, their finances, their geography and whether they shop online, in-app or in-store. It would be counterproductive, for instance, to run a print-led campaign for an e-commerce business with an expanding social media following. Similarly, for a company whose target audience subscribes to a specific mix of print newspapers, it would be far more effective to reach out to the editors of the relevant supplements or desks at these titles instead of pursuing influencer PR opportunities on Instagram.

A great example could be a company selling beautiful, handmade handles for kitchen cupboards and drawers. They might hand-craft each product and may not have the facility to ship internationally, choosing instead to focus on their UK customer base, easing pressure on their craftspeople. For this business, the PR campaign should respond to and facilitate these commercial goals, positioning its products in British design magazines read by home renovators, or trade publications read by kitchen designers. They could also look towards home-interest social media accounts with a high engagement for gifting opportunities in return for exposure, tags and mentions. The big brand story in Forbes or in the internationally poured-over FT How to Spend It can wait until the CEO is ready to take their business to the next level, adjusting the objectives of the PR campaign to support this. 

Your PR agency or consultant will be able to guide you seamlessly through the process of increasing your share of voice in the right media, be it locally, nationally or internationally. They are often the source of the most creative, dynamic ideas when it comes to storytelling, product launch proposals, events, photoshoots and collaborations. A good agency will support and advise you based on wider industry trends from their vantage point at the centre of the communications world, always at the ready with your brand’s name front of mind. Of course, they’ll be the first to raise a glass to your Absolutely Fabulous successes, too. 

Finances in a time of COVID-19

With the world overtaken by the current healthcare crisis of COVID-19, we all face much uncertainty and many challenges ahead, both personal and professional. Keeping ourselves and our loved ones healthy is of course the main priority for everyone right now, but when this is over, and it will be over, we face the question… what then?

Some of us may not have jobs to return to and many of those who do return to employment will face a different landscape and work culture for sure, perhaps with an altered salary too. But for those who are self-employed or run small businesses (or even large ones), it can feel like a lonely survival battle as work changes shape and income wavers.

We wanted to share with you some advice from BBB Partners ‘We’ll Mind Your Own Business’ (WMYOB) who specialise in accounting and bookkeeping, tax calculations, submissions and tax credits, payroll and pensions management, meaning they are perfectly positioned to advise BBB members across a variety of financial situations. WMYOB sent us their guidance as finance professionals and we hope you will find useful.

(All info correct at time of publishing but please seek professional advice if later).

Job Retention Scheme and Statutory Sick Pay (SSP)

The Government has announced that under the Job Retention Scheme, all UK Employers will be able to access support to continue paying part of their employees’ salary – where they would have been otherwise laid off. This does mean that the employee must take up a “furloughed” status and must not conduct any work for the business during this time. If this is the case, then HMRC will reimburse 80% of the worker’s wage costs, up to a cap of £2,500 per month. It is the employer’s choice whether they ‘top-up’ the employee’s salary by the further 20%, or indeed beyond the cap – but this is not compulsory.

The scheme is due to run for at least three months from 1st March 2020 but may be extended if necessary. Although originally, it was only related to those workers who were in employment as of 28th February 2020, as of 15th April 2020, the eligibility of the scheme extended to 19th March 2020. However, an RTI submission notifying payment in respect of that employee must have been made to HMRC on or before 19th March 2020 in order for them to qualify.

Employers will be able to use a portal to claim for 80% of ‘furloughed’ employees’ usual monthly wage costs up to the cap of £2,500, plus the associated Employer National Insurance contributions and minimum automatic enrolment pension contributions. These contributions on any additional top-up salary, as decided by the employer, will not be funded through the scheme though.

It is unlikely that any contract in place with employees will contain a clause around furloughing and therefore it is important to discuss these changes directly with employees and gain their written approval over their furloughed status. There should be written evidence that this communication has taken place and both parties agree to the implications. This should also include the date that the status was changed and you should ensure they undertake no further work beyond this date to be eligible for the scheme.

It is possible for an employee who has more than one job to be furloughed. Each job is to be treated as separate and the cap will apply to each employee individually. If the individual’s pay varies and they have been employed for a full 12 months prior to the claim, there are two options available, whereby you can claim the higher of:
– The same month’s earnings from the previous year (ie April 2019)
– The average monthly earnings from the 2019-20 tax year.

If they have been with you for less than a year, it would simply be the average earnings for the months completed so far, and if they joined in February, use a pro-rata calculation for their earnings to date.

You can submit one claim at least every 3 weeks – which is the minimum length an employee can be furloughed for. In order to make a claim, although WMYOB can of course assist you with this as part of their services, you will need: a PAYE reference number, number of employees being furloughed, the claim period, amount claimed, bank account/sort code for payments to be made into, contact name and phone number. Payments will be made by BACS into the provided UK bank account once they have been received and reviewed.

HMRC do retain the right to retrospectively audit all aspects of your claim.

Self-Employment Income Support Scheme

The Chancellor also announced a support package to those who are Self-Employed and have lost income due to COVID-19. This scheme will allow those who are Self-Employed to claim a taxable grant worth 80% of their trading profits for the next 3 months.

This scheme is not open yet and HMRC will contact you if you are eligible for the scheme and invite you to apply online.

To qualify, you must:
– Have submitted your Income Tax Self-Assessment for the tax year 2018-19 (If you have not submitted this return yet, the deadline has been extended to 23rd April 2020)
– Traded in the Tax Year 2019-20
– Are trading when you apply, or would do except for COVID-19
– Intend to continue to trade in the tax year 2020-21
– Have lost trading profits due to COVID-19.

You must also have trading profits of less than £50,000 and demonstrate that more than half your income comes from Self-Employment.

You will receive a tax grant up to 80% of the average profits from the tax years 2016-17, 2017-18 and 2018-19.

In addition, or in replacement, of this scheme, there is further help available through the deferment of Self-Assessment payments due in July 2020 until January 2021, increased amounts of universal credit and the business interruption loan scheme.

Should you have any further questions about these schemes or anything else that WMYOB might be able to help with, please do get in touch.

Deferring VAT and Income Tax payments

The government has announced a 3-month deferment in Valued Added Tax (VAT) payments for all UK businesses. Consequently, any payment which would have been due at any point in the period 20th March 2020 and 30th June 2020 will now have been deferred automatically. You will now have up until the end of the 2020/21 Tax year to pay any liabilities accumulated during this period. VAT refunds and reclaims will be paid by the government as normal.

It was also announced by the Chancellor, that anyone who has Self-Assessment payments due on 31st July 2020 will also have these deferred – until 31st January 2021 in this case.

In addition to the above, HMRC has also extended the scope and availability of its ‘Time to Pay’ service. This will allow companies to come to a specific arrangement with HMRC on the payment of it’s other tax liabilities. WMYOB can assist in making the call and negotiating with HMRC in this instance if helpful.

Support with Business Rates

The Chancellor also introduced business rates holidays for businesses in sectors that the Government considered could be most adversely affected by the outbreak.

These include:
– Business rates holiday for retail, hospitality and leisure businesses.
– Cash grants for retail, hospitality and leisure businesses.
– Businesses that pay little or no business rates because of small business rate relief (SBBR) or rural rate relief (RRR) are eligible for a one-off grant of £10,000 to help meet their ongoing business costs.

In almost all cases, your local authorities will send through updated business rates to you and therefore this will occur automatically. If this has not been the case, or you feel you qualify for any of the above please do get in touch and we would be happy to review this alongside you.

Coronavirus Business Interruption Loan Scheme (CBILS)

You could also be eligible to access the new Coronavirus Business Interruption Loan Scheme – which allows access to working capital up to £5 million. The government will pay to cover the first 12 months of interest payments and any initial set-up fees – although some providers have already waivered these. To give lenders further confidence in continuing to provide finance to SMEs the government will provide lenders with a guarantee of 80% on each loan (subject to a per-lender cap on claims).

There are currently 40+ lenders who are signed up to this scheme and you should apply with them directly. WMYOB will be delighted to assist in putting the application pack together – which will have to include a borrowing proposal which were it not for the current pandemic, would still be considered viable.

**WMYOB** are happy to discuss these issues or anything else with BBB members and Partners, just get in touch for an intro to the most suitable person on the team at info@thebbbook.com.